Skip to content

Major losses. Careful coordination.

Catastrophic Property Loss & Complex Insurance Claims

A major property loss can interrupt operations, displace occupants and bring several insurers, contractors and financial interests into one dispute. Sotero Law helps commercial owners, associations and insured businesses evaluate the coverage, documentation and legal issues that determine the next steps.

PRACTICAL PERSPECTIVE. LEGAL PURPOSE.

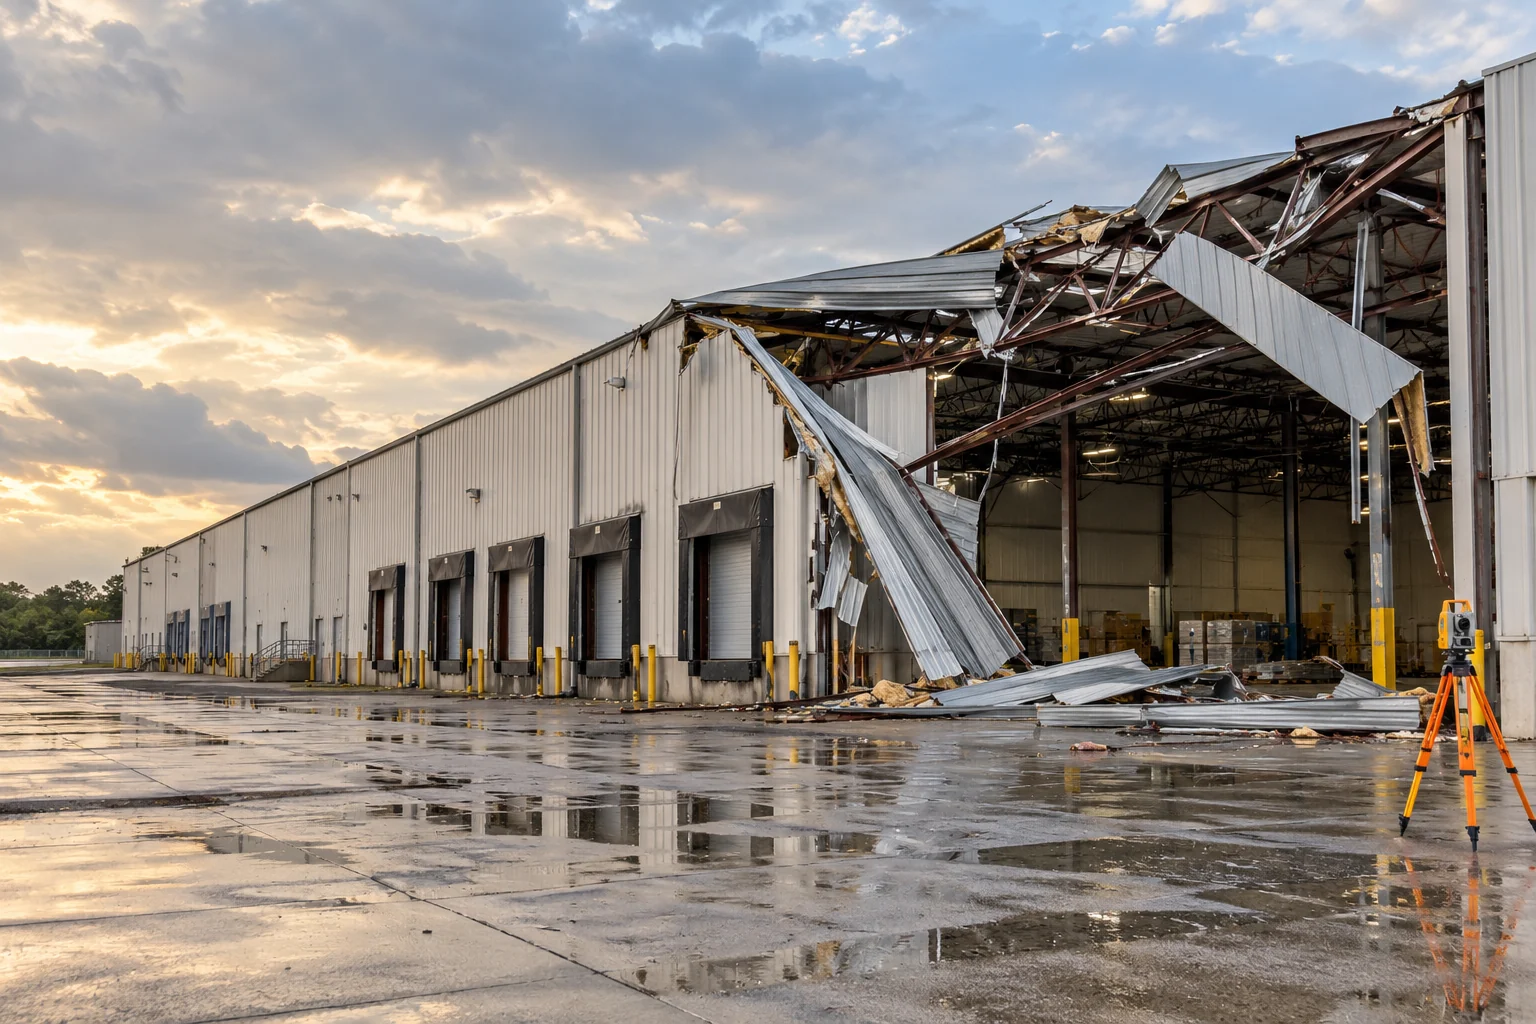
Industrial warehouse with storm-damaged roof and professional inspection equipment.

YOUR CIRCUMSTANCES. YOUR OBJECTIVES.

A loss that extends beyond the building

A damaged warehouse, commercial property or multi-building development can present several questions at once: what caused the damage, which property was insured, what a reasonable repair requires and which financial losses fall within the policies. A large estimate alone does not answer those questions. Each part of the claim needs a clear factual and contractual foundation.

The practice focuses on substantial property damage and complex insurance disputes, including hurricane, wind, fire, water and other losses where coverage may apply. Sotero Law organizes the relationship between physical damage, policy terms, restoration work and continuing operations so that the legal strategy addresses the actual loss.

HOW SOTERO LAW CAN HELP

Policy and coverage review

Identify insured interests, coverage layers, conditions and disputed policy provisions.

Damage and repair disputes

Connect the event, inspection record, restoration scope and supported valuation.

Business income and expense

Evaluate purchased coverage and the records supporting an interruption-related claim.

Coordinated dispute strategy

Assess correspondence, procedural obligations and appropriate resolution options.

Identify the policy before assuming coverage

A coordinated review starts with complete policies, schedules and endorsements. Primary and excess coverage, named insureds, covered locations, deductibles, exclusions and notice provisions can affect the available options. A certificate or declarations page may identify a policy without explaining its limitations.

Wind and flood require separate attention. National Flood Insurance Program coverage does not include business-interruption losses. Private flood insurance and commercial property policies require their own review. A storm, evacuation or business closure does not by itself establish coverage for every resulting expense.

Connect technical findings with the financial record

The claim should connect observed damage to the event, repair scope and supported cost. Photographs, inspection findings, prior maintenance, original plans, mitigation invoices and contractor estimates can help explain both the condition of the property and the proposed restoration. Independent engineers, estimators or accounting professionals may be appropriate depending on the issues.

Business-income and extra-expense claims involve a separate record. Purchased coverage, applicable triggers, the restoration period, operating history and documented expenses matter. Financial projections should be tied to records and explained assumptions, rather than treating all reduced revenue as an insured loss.

Choose the next step from the facts

An underpayment, scope disagreement and coverage denial may require different responses. Sotero Law examines claim correspondence, information requests, inspections and available dispute-resolution provisions before evaluating negotiation, appraisal, mediation or litigation. Each route has limits; no process guarantees payment or resolves every issue.

Notice, proof-of-loss and lawsuit deadlines are distinct. Florida rules also differ by coverage classification and claim circumstances; the sixty-day pay-or-deny provision is not a universal rule for all large commercial policies. Federal flood claims have separate requirements. Prompt review helps identify the obligations that actually apply.

Insurance and construction experience inform the review

Before entering legal practice, Albert Sotero developed and managed commercial insurance programs. His background includes underwriting, program administration, captives, reinsurance and claims-administration arrangements. His construction and development experience adds practical context to building conditions, repair scope and the operational effects of a prolonged loss.

That prior business experience informs legal analysis; it is distinct from his legal career. He was admitted to The Florida Bar in 2024. The engagement begins by identifying the client, checking conflicts and defining the matter to be addressed.
Frequently asked questions

Does a major loss automatically qualify for policy limits?

No. Available recovery depends on the insured loss, policy provisions, applicable law and evidence. The scale of the event does not eliminate exclusions, deductibles or the need to substantiate the claim.

Can lost business income be part of the claim?

Potentially, if the relevant coverage was purchased and its conditions are met. Business income, extra expense and physical damage are distinct issues. NFIP policies do not cover business interruption.

Should repairs wait until every dispute is resolved?

Safety, mitigation, evidence preservation and policy duties must be considered together. Obtain case-specific guidance, document conditions and necessary work, and retain invoices and relevant communications.

What if different insurers attribute damage to different causes?

The policies, causation evidence and claimed amounts need a coordinated review. Identify each insurer and preserve the original evidence rather than assuming one policy must cover everything.

RELATED READING

General information, not advice for a particular matter. Facts, policies, contracts, governing law, and deadlines require individual review. A consultation request does not create an attorney-client relationship or stop a deadline.

LET’S DISCUSS WHAT COMES NEXT

A clear view of your next move.

Request a Consultation